Give customers a convenient way to pay and your business a clear view of cost and available funds. In Indonesia, those decisions belong together: the payment method, fixed charge and settlement terms can matter more than a headline percentage.
This guide brings together a commercial snapshot supplied by gateways and practical questions for choosing a partner. Explore 75 recorded offers, pay-in and payout fees, settlement labels, QRIS and the requirements for a lawful launch.
75 offers: a starting point for comparison
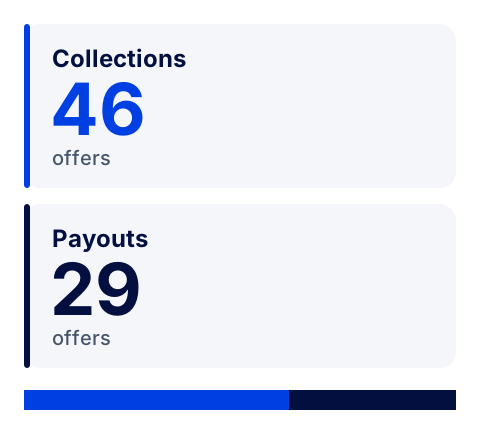
The snapshot of 14 September 2026 contains 75 unique offer records associated only with Indonesia: 46 pay-ins and 29 payouts. This describes the saved sample, not independent gateways, live integrations or approved payment routes.
Start with your use case: one-off purchases, recurring invoices, refunds or bulk payouts. Request separate terms for each, including currency, method and company requirements. Country, currency and method links in the catalogue are independent; their presence does not establish that the combination your business needs is available.
Turn the percentage into a complete cost picture
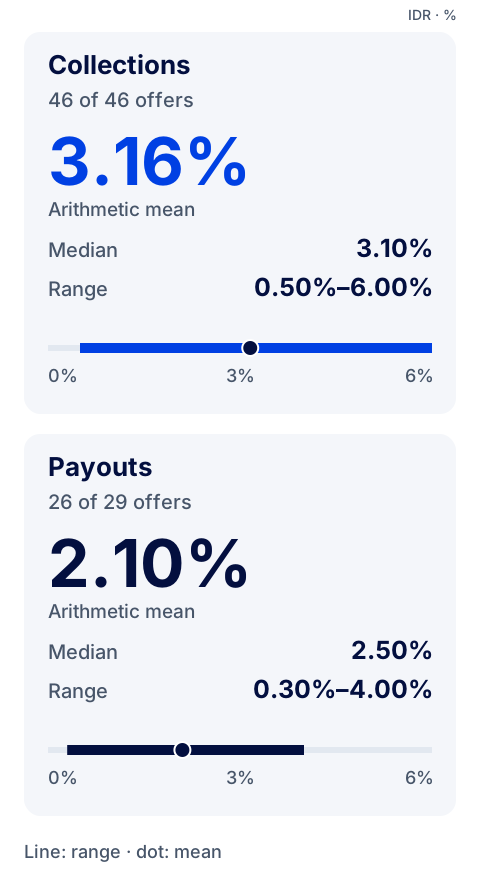
The mean stated IDR percentage fee component is 3.16% for pay-ins, n=46, and 2.10% for payouts, n=26. These are unweighted record averages, not volume-weighted costs. Three payout offers contain no explicit percentage and are excluded from that calculation.
Check the fixed component too. It appears in 14 of 46 percentage-bearing pay-in offers at IDR 5,000–7,000, and 22 of 26 payout offers at IDR 4,500–7,000. These amounts are excluded from the percentage means. An unfilled fixed-fee field does not establish that there are no extra charges.
This matters for smaller purchases. An illustrative example, not an offer: a fixed IDR 5,000 is 5% of an IDR 100,000 payment and 0.5% of IDR 1,000,000, before any percentage fee. Compare total costs against your transaction-size distribution, including refunds, FX, taxes, settlement transfers and reserves.
T+0: establish when you can use the money
T+0/D+0 appears in 24 of 46 pay-in offers. Other records state T+1/D+1 in 10 offers, T+3/D+3 in nine and T+7/D+7 in three. These are gateway labels, not verified timings for funds reaching your business.
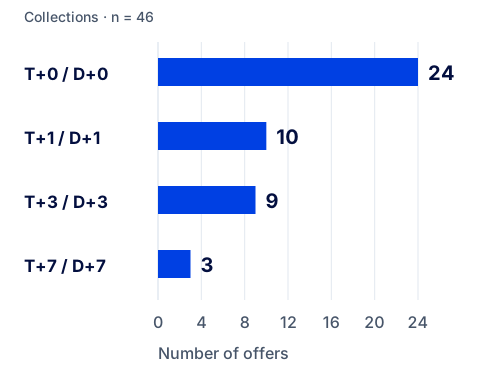
Ask what starts T or D: successful payment, statement closure or settlement approval. Then agree the cut-off and time zone, calendar or business days, minimum transfer amount, reserve and receiving currency. A quickly confirmed purchase and an available merchant balance are different events.
The cover line “3.16% / 2.10% · T+0” combines two averages and a separate timing label from the sample. It is not one tariff or a promise that all three terms are available in a single offer.
QRIS and BI-FAST: design around the customer journey
QRIS is the national QR payment standard. For a merchant, the practical questions are onboarding with an approved provider, confirming the amount and order, refunds and reconciliation. The standard’s existence does not prove that a historical catalogue offer suits your website, business activity or legal entity. Bank Indonesia: QRIS.
Check the upcoming pricing change separately. Bank Indonesia announced that from 1 October 2026, 0% QRIS MDR will extend to payments up to IDR 100,000 across merchant categories; the IDR 500,000 threshold for microbusinesses remains. That effective date is still ahead of the editorial review on 29 September. This is an MDR policy, not confirmation that an entire gateway service is free. Request a price breakdown and confirmation of your category. BI announcement of 17 August 2026.
BI-FAST is real-time retail transfer infrastructure operating 24/7. That network characteristic does not guarantee gateway T+0 settlement or establish cross-border settlement. If a provider proposes bank transfers, ask which network is used, what the account is intended for and how each payment is matched to an order. Bank Indonesia: BI-FAST.
Limits and conversion: questions before integration
All 75 offers have recorded limit fields, but those fields cannot be merged into one universal acceptance range. Agree minimum and maximum transaction values by method, daily restrictions, beneficiary limits and what happens when an amount exceeds a limit. For payouts, clarify account-holder requirements, name checking and failed-operation charges separately.
The source contains no measured average conversion rate. One gateway makes a claim, but comparable transaction evidence, an observation period and a denominator are absent. Request results for your business activity, devices and payment method: payment started → confirmed payment → available funds. Clarify how retries, expired QR codes and unfinished transfers are counted.
Before selecting a partner, ask for a sample reconciliation statement: order reference, transaction identifier, status, currency, fee, refund and settlement date. This helps compare the future workload for your finance team as well as the price.
Indonesian licensing and authority requirements
PBI No. 10/2025 has applied since 31 March 2026. PJP activity requires the applicable Bank Indonesia authorisation; check the provider’s permitted services and current status. Existing permissions continue under transitional rules. A provider’s licence does not replace permissions required for your product. Bank Indonesia: PBI No. 10/2025.
Prepare company, ownership, product, customer and funds-flow information for provider review. Technical integration does not remove either party’s payment obligations. The regulation provides for BI approval when processing outside Indonesia; the specific architecture and any applicable exceptions need separate assessment. PBI No. 10/2025, Article 122.
Online gambling is prohibited; a foreign licence does not make it a permissible local product. The prosecution service explains the application of ITE provisions and Articles 426–427 of the new criminal code to organisers and players. Payment selection is not a way around that prohibition. Indonesian prosecution service: 2026 explanation.
Article 119 of PBI No. 10/2025 prohibits PSPs from using virtual currency as a source of funds in payment processing or linking it to payment processing. This should not be expanded into a blanket prohibition on all regulated cryptoasset trading. PBI No. 10/2025, Article 119.
PayStar’s role
PayStar provides information and technology for integration. PayStar does not act as a bank or payment service provider (PSP), and is not a payment organiser. PayStar does not organise payment acceptance or settlement in its own name: it does not receive, hold or settle customer or business funds. The business selects the payment provider and contracts with it directly; that provider processes transactions and settles funds under the agreement. Terms, availability and onboarding decisions are confirmed separately.
PayStar works only with lawful products holding the licences and permissions required for their activity and territory. This is PayStar’s operating principle, not a claim that all 75 historical offers have verified licensing or suit every product. The catalogue starts a focused conversation; provider authorisation and business eligibility must be established before launch.
Get details on payment gateways in Indonesia
Send Anastasia your company’s registration country, product description, average transaction value, monthly volume and required directions: pay-ins, payouts or both. Add your preferred payment methods and settlement currency.
Request percentage and fixed fees, limits, settlement timing and currency, and product and documentation requirements. Information is free; integration, payment processing and subsequent services are discussed separately. The provider confirms availability and onboarding eligibility.