When comparing payment providers in Ecuador, describe where the sale happens before asking which payment methods are supported. A customer at a counter can scan a displayed QR. Someone ordering through a message needs a payment request they can open on the same phone. A business paying suppliers needs a separately qualified outgoing service.
Deuna provides a useful local example of why these distinctions matter. Its different collection experiences are not interchangeable. Compare the customer's steps, the merchant's evidence and the movement of funds for each proposed setup.
Choose the collection model for the sales channel
Deuna's enterprise guidance distinguishes a static QR where the customer enters the amount from integrated options where the business supplies it. Its dynamic QR is transaction-specific and stops working after use. Payment links require API integration and work on the customer's phone through the Deuna app. The enterprise page also describes payment-status enquiries and successful-payment notifications to the merchant's system. Deuna: solutions for companies.
For counter sales, decide who enters the amount and how staff check it. For remote orders, request a demonstration on the customer's phone: opening the link, moving into the payment app and returning to the order. Confirm which customer apps work with the exact collection option. Support for a QR experience does not establish identical support for a link.
Ask the PSP to demonstrate how your order number survives the whole journey. The useful result is a matched sale with an amount, currency, transaction reference and final status that staff can retrieve. Treat these as acceptance criteria to verify, rather than features implied by a method logo.
Test a counter sale and a remote order together
Consider a hypothetical Quito food business taking two orders: USD 12 at the counter and USD 28 for delivery. Total sales are USD 40. The counter customer scans a displayed QR; the delivery customer receives a payment link. These are illustrative amounts, not a client case or a provider tariff.
The merchant should be able to connect each confirmed payment to the right order and distinguish payment confirmation from the later bank credit. If the counter customer enters an incorrect amount, staff need a documented correction process. If the remote customer abandons payment, the delivery order must remain visibly unpaid. Test both situations before launch.
Now suppose the delivery order loses an unavailable USD 8 item. The agreed retained sale becomes USD 20, and the combined retained sales become USD 32 before fees. Ask the PSP how a partial refund is requested, approved and linked to the original USD 28 payment. Confirm whether that operation is supported and which funds finance it.
Deuna's enterprise page lists refund/cancellation functionality and separates sales reports from reports of payments to the business. Use those distinctions when requesting sample statements. A collection record, a refund and a consolidated bank payment should be reconcilable without treating all three as sales. Deuna enterprise operations and reports.

Offline payment has its own conditions
Deuna also documents an offline process for friends and microbusinesses with a Deuna account. The recipient must scan the QR on the payer's receipt in the app. The FAQ says funds become effective when either party reconnects, with that receipt-verification step completed. It lists up to three offline payments totalling USD 15 per day, and payment within four hours of the payer's last connection. Deuna: payments without internet.
This is a specific app procedure, not evidence that an enterprise API or online checkout works offline. If a business intends to use it, confirm current eligibility, app version and limits. Train staff on the actual verification step and establish how they track transactions until completion. A screenshot shown by the customer should not replace the documented in-app procedure.
Agree when staff may release goods, how unresolved receipts are investigated and who decides whether to offer another method. Confirm these operating policies with the provider before relying on offline payments.
Qualify the business account and USD payouts separately
The Deuna Negocios app's onboarding guidance requires an Ecuadorian identity document, an active RUC, an active personal Deuna account and the business's legal representative. It also describes specific supported accounts for moving the app's balance. These are requirements of that app journey, not a universal onboarding rule for every Ecuador PSP or proof of foreign-company eligibility. Deuna Negocios app guidance.
Provide your company structure and receiving-account requirements. Obtain settlement schedules, deductions and account restrictions in writing. Confirm whether collections can fund supplier payments or a separate balance must be prefunded.
For bank payouts, Ecuador's central bank describes SPI as electronic transfers through participating financial institutions to individuals and companies with accounts in Ecuador. It publishes processing cut-offs. This domestic infrastructure description does not establish a particular PSP's API coverage or an overseas settlement service. Banco Central del Ecuador: SPI.
Request recipient coverage, beneficiary checks, submission deadlines, charges and item-level results for the intended payout service. Establish what happens to a rejected instruction and when an uncertain result can safely be retried. A successful local collection is not evidence that every outgoing destination is available.

Build a shortlist around the complete transaction
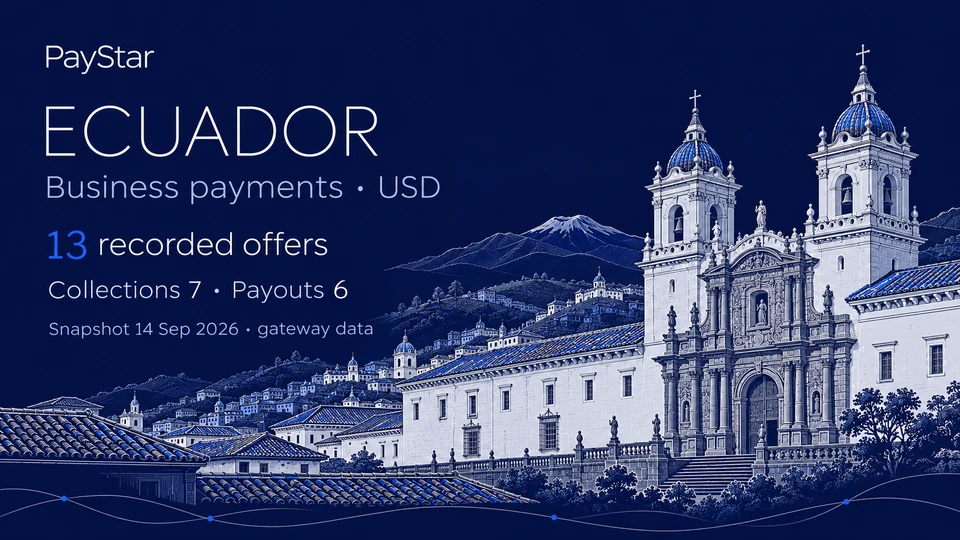
PayStar's 14 September 2026 snapshot contains 13 unique recorded payment offers associated only with Ecuador: seven collections (Deposit) and six payouts (Withdrawal). All thirteen have a USD association. These are offer records, not independent PSPs, live integrations or approved routes. Separate country, currency and method links do not prove every combination, including the Deuna examples above.
Want information about these payment options for free? Just write to us. Contact Anastasia through PayStar Discovery with your business activity, registration country, sales channels, expected amounts and collection/payout requirements. Discovery helps structure the shortlist and qualification. Free information does not include integration, processing or all subsequent services. The merchant chooses and contracts directly with the PSP, which decides approval and provides processing and settlement under its agreement. Current availability and eligibility require confirmation.

PayStar’s role
PayStar provides information and technical services. PayStar is not a bank or PSP, does not arrange payment acceptance or settlement in its own name, does not receive or hold customer or merchant funds, and does not settle those funds. Payment services are provided by the selected provider under a direct agreement with the merchant. PayStar’s API, routing and monitoring operate within the agreed technical role.