What is the risk for businesses?
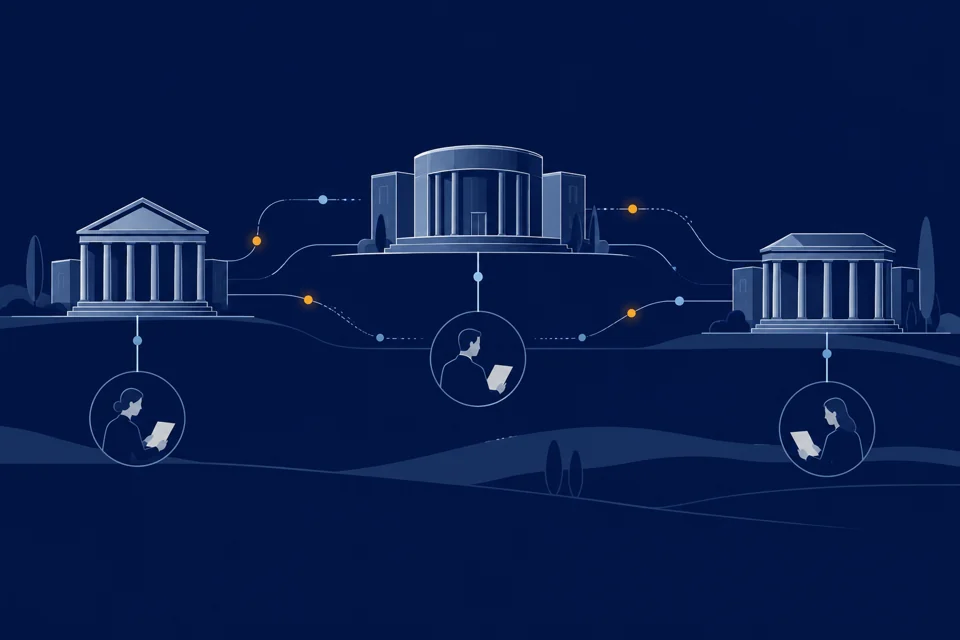
Imagine your main PSP is reviewing a suspicious transfer. Your company plans to continue operating through a backup partner. But if that partner participates in information sharing and receives the same alert, it may also have questions.
This is a possible scenario, not an automatic block. FRIDA shares information; each PSP decides how to respond.
A backup provider remains useful during a technical outage. It does not guarantee that questions about a transaction disappear when you switch providers.
What should you check in advance?
For the CEO: can the backup PSP keep serving the business? Ask the partner how it handles external fraud alerts, who investigates errors and which documents it would need. Having a second PSP connected is not enough on its own.
For the CFO: can you fund the next payouts? If the main PSP temporarily restricts access to funds, how will the company meet its obligations? Count usable funds, not the total balance shown in dashboards. This is ordinary preparation for PSP reviews, not a new FRIDA requirement.
Do you need to change anything now?
There is no need to urgently redesign your payment setup because of FRIDA. As of 22 October 2026, the rules are still under consultation. The initial scope concerns account-to-account transfers within the boundaries described by the EPC; it does not automatically extend to all card and crypto payments.
For now, find out how your partners handle such alerts and check your payout reserve. Revisit integrations or routing changes when the final rules and your PSPs' participation become clear.
Sources: EPC explanation, draft rules and consultation.