A membership business comparing payment providers in the United Kingdom needs more than a list of accepted methods. It needs to know when a scheduled bill becomes a collection, how an unpaid item reaches the finance team, and what happens if the customer pays another way while the original collection is still in progress.
Bacs Direct Debit and Faster Payments address different parts of that job. A useful provider comparison follows one invoice through its due date, exceptions and any refund.
Start with a dated view of the options
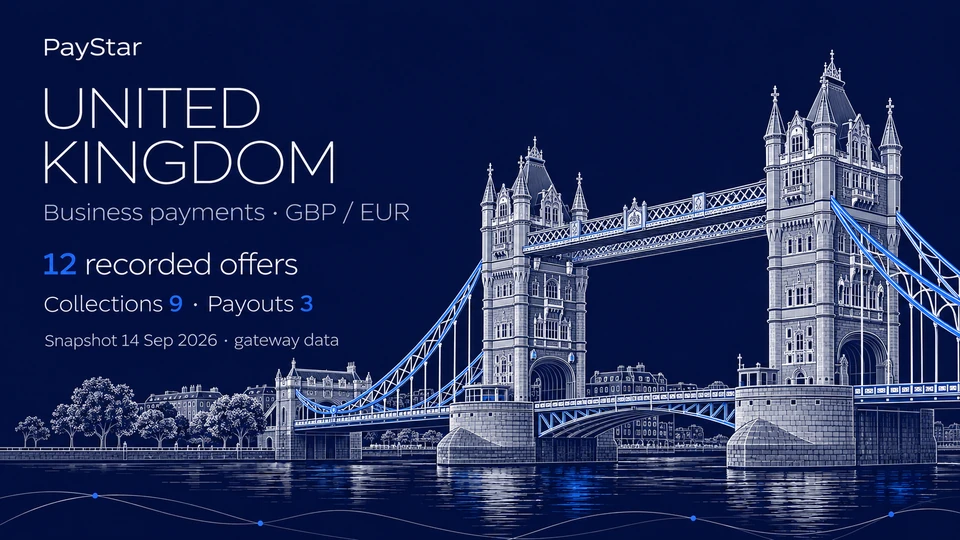
PayStar's 14 September 2026 snapshot contains 12 unique recorded payment offers associated only with the United Kingdom: nine labelled Deposit and three Withdrawal. Nine of these offers have a GBP currency association and five have EUR; the groups overlap, so they do not represent fourteen offers.
This is a research starting point, not a count of independent providers or live connections. Separate country, currency and method associations do not establish every possible combination. Each provider still needs to confirm the required method, business eligibility and current commercial terms.

Direct Debit starts before the collection file
A Direct Debit Instruction, often called a mandate, records the customer's authority for the organisation to collect from their account. The official setup guide describes instructions made online, by telephone or in writing. It also states that this Direct Debit scheme requires a UK bank account; an EUR association in a database does not establish EUR Direct Debit support. Direct Debit setup guidance.
Before choosing a provider, establish who handles mandate setup, confirmation, advance notices and changes. The Direct Debit Guarantee describes notice of changes to amount, date or frequency as normally ten working days, or another agreed period. Confirm the applicable arrangement rather than building a universal ten-day rule into your billing system. Direct Debit Guarantee.
This separates customer onboarding from the processing time of an individual collection. A newly completed signup is not evidence that tomorrow's bill can already be collected.
Work backwards from the payment date
Bacs defines its cycle as three English bank working days: input, processing and entry. On entry day, the payer is debited and the collecting account credited. The provider's submission deadline and any subsequent transfer to your own bank account also need to be understood. Bacs glossary.
For a hypothetical Monday collection, with no relevant bank holidays, Thursday input and Friday processing lead to Monday entry. That illustration assumes the mandate, notice and provider deadlines have already been satisfied. Weekend and bank-holiday due dates normally move to the next working day unless a changed date is notified in advance. Managing Direct Debits.
Ask for a calendar that distinguishes the customer due date, provider cutoff, collection entry and merchant remittance. The word “settlement” alone does not identify which event a proposal means.

One invoice, two ways to pay
Consider a hypothetical UK membership company billing 200 customers at GBP 45, a scheduled total of GBP 9,000 before fees or unpaid items. One customer wants to pay their GBP 45 invoice by bank transfer while its Direct Debit is already submitted.
If both payments complete, GBP 90 has arrived against a GBP 45 invoice. Faster receipt has created an overpayment that needs reconciliation.
The useful provider questions are operational: can that individual collection still be recalled, who confirms the outcome, and when is an alternative payment request safe to send? Bacs describes recall after submission as subject to notifying the bank before its cutoff; it is not an unconditional cancellation button. Bacs Direct Debit process.
Keep both payment references against the same invoice. Once a collection is confirmed unpaid, a catch-up request can follow the agreed recovery process. If a submitted collection is still uncertain, require an explicit decision instead of sending a second demand automatically. This is a proposed operating control, not a claim about every provider's API.

Unpaid collections and refunds need separate treatment
Bacs provides ARUDD reports identifying unpaid Direct Debits and their reasons. Ask how the provider delivers those outcomes, who reviews them and how repeat attempts are authorised. A submitted file alone does not show that every invoice was paid. Bacs report definitions.
A commercial refund, an unpaid collection and a claim under the Direct Debit Guarantee also need distinct records. The Guarantee addresses errors in a Direct Debit and explains that it does not alter the underlying contract with the biller. Ask the provider how claims, customer refunds and later balance adjustments appear in reports; do not treat a payment-status label as the whole customer account. Direct Debit Guarantee.
Qualify GBP payouts separately
Faster Payments can be relevant to individual business payments. Pay.UK says payments between direct participants usually reach the receiving account almost immediately, sometimes within two hours, and some payments take longer. Once sent they cannot be cancelled through the normal payment flow; the banking industry's recovery process addresses mistakes. How Faster Payments work.
For GBP payouts, confirm recipient requirements, funding, limits, approval controls and exception handling separately from collections. Banks can impose limits below the scheme ceiling; domestic transfer speed does not promise cross-border settlement. Faster Payments transaction types.
Bring the calendar to the shortlist
Share your business activity, company jurisdiction, billing frequency, typical amount, expected volume and payout needs with PayStar Discovery. Add the deadline for customer access and your process for failed or duplicate payments. That gives a provider something concrete to qualify.
Want information about these payment options for free? Just write to us. Contact Anastasia through Discovery. Free information does not include integration or processing. The merchant selects and contracts directly with the PSP, which confirms eligibility, processes payments and settles funds under its agreement. PayStar helps structure the comparison without guaranteeing approval or availability.
PayStar’s role
PayStar provides information and technical services. PayStar is not a bank or PSP, does not arrange payment acceptance or settlement in its own name, does not receive or hold customer or merchant funds, and does not settle those funds. Payment services are provided by the selected provider under a direct agreement with the merchant. PayStar’s API, routing and monitoring operate within the agreed technical role.